Structure and Governance
This theme seeks to assess our overall structure and approach to governance.
Strong governance helps Great Places maintain service standards, manage risk and improve outcomes for customers.
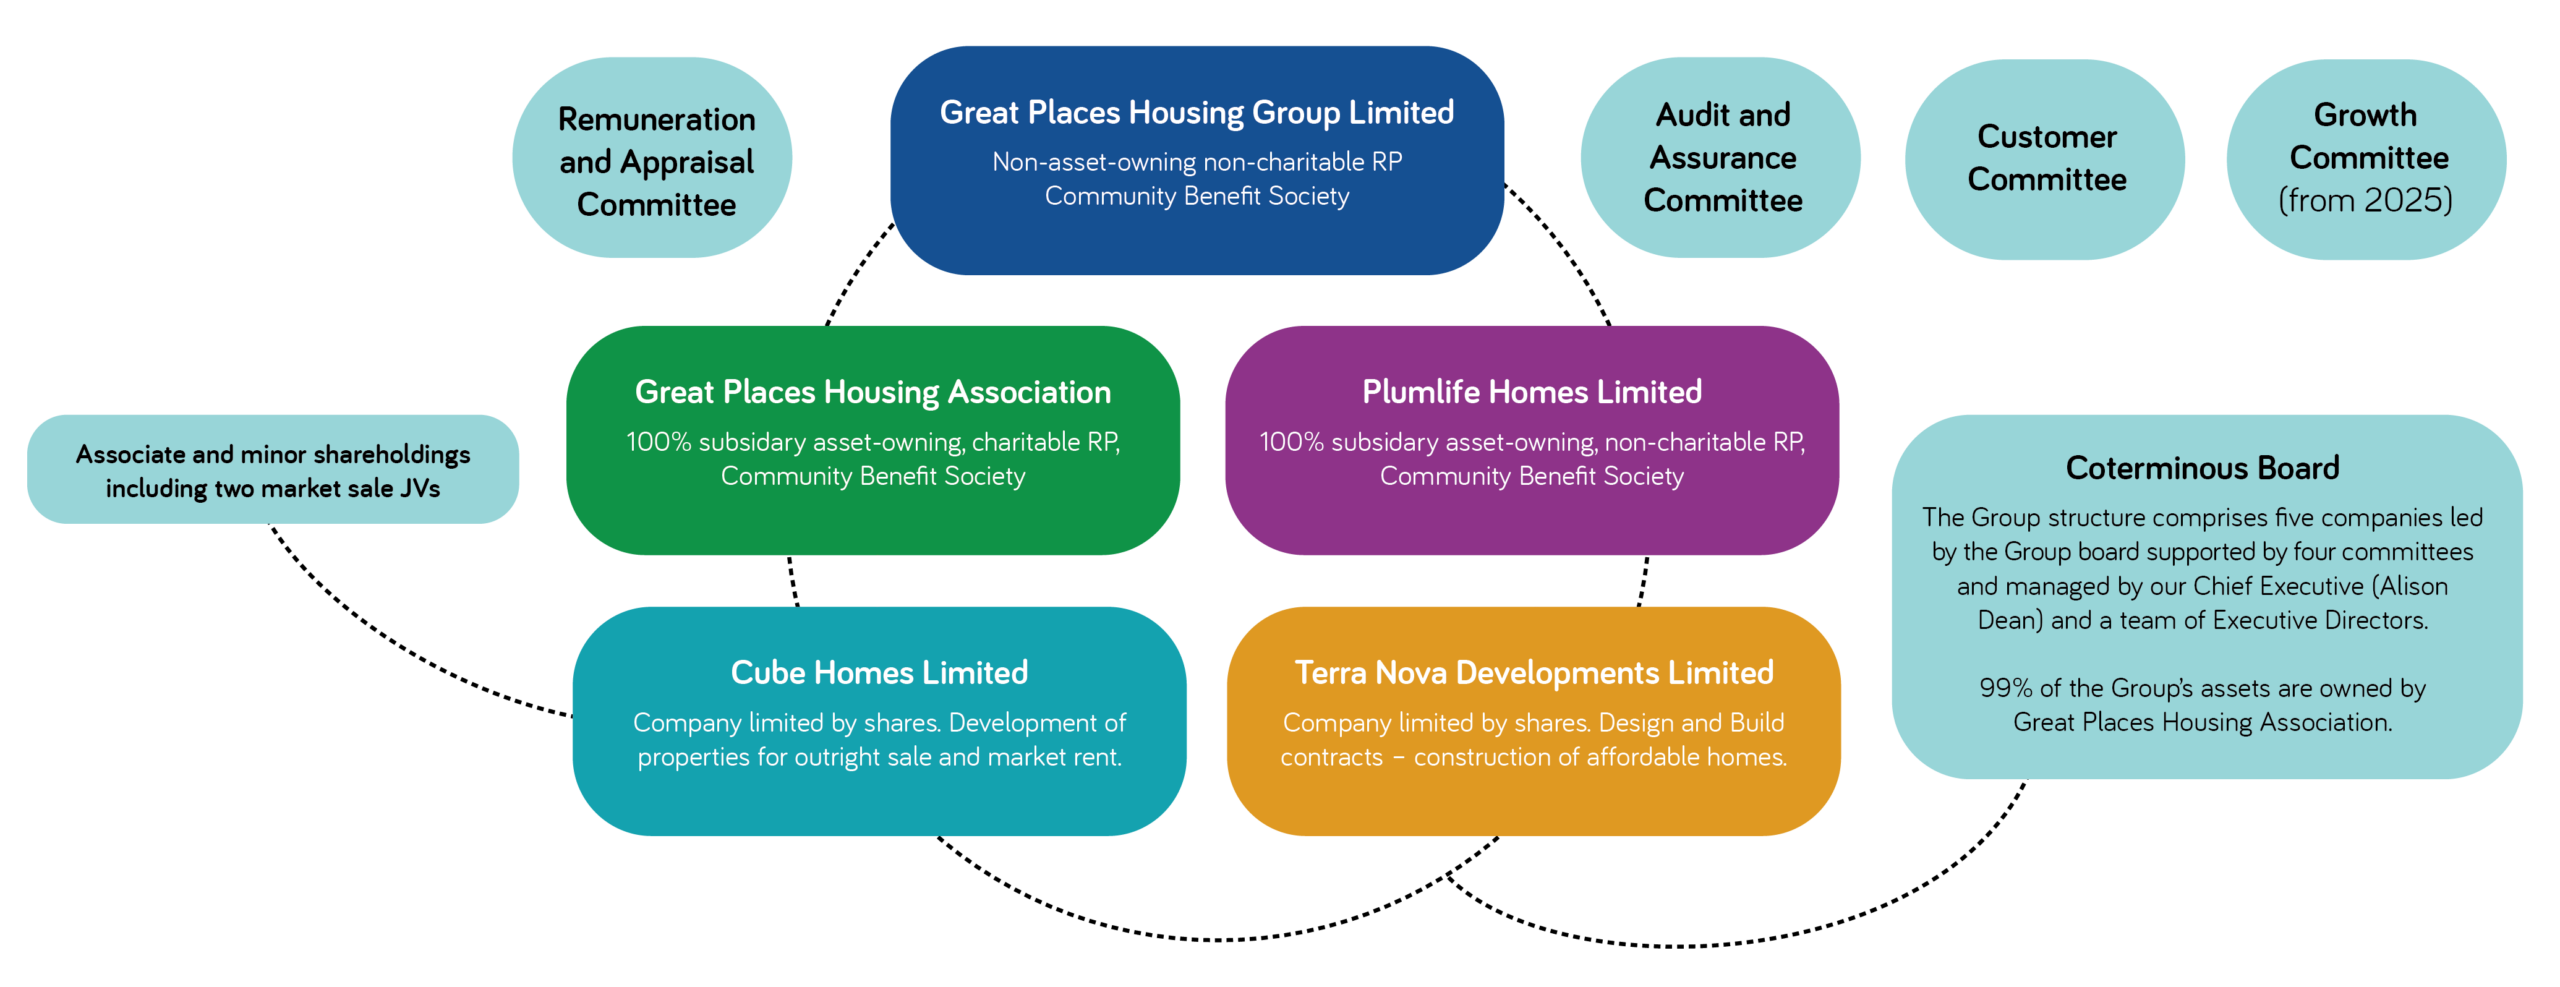
(Accessible version of structure)
Great Places Housing Group Limited is a registered housing provider and the parent company of Great Places Housing Association, a not-for-profit organisation with charitable status, and Plumlife Homes Limited. Both Great Places Housing Group and the Housing Association operate on a profit-for-purpose basis, with surpluses reinvested in new homes, services and communities.
As a Registered Provider, we are regulated by the Regulator of Social Housing and currently hold a G1 governance rating and a V2 financial viability rating, confirmed in our most recent inspection in September 2024. We also received a regrade to C1 this year under the new Consumer Standards, up from C2 the previous year, reflecting our commitment to improving customer experience and compliance.
Despite sector challenges – including inflation, rising interest rates, and the cost-of-living crisis – the Regulator has confirmed our financial resilience and ability to manage risks, including those linked to development and sales.
We follow the National Housing Federation Code of Governance 2020 and have had no adverse regulatory findings in the past year, zncluding in areas such as data protection.
Customer feedback is gathered through our independent Customer Scrutiny Group (Insight), which conducts reviews and reports findings to the Board and Customer Committee. These are considered alongside Tenant Satisfaction Measures, complaints data, and wider customer feedback.
Signals of Progress:
Consumer Standards rating improved from C2 to C1 in December ’25, reflecting progress in customer experience, service delivery and compliance
Risk management
Effective risk management supports good decisions and strong day-to-day management. It helps us understand the opportunities we want to take and the risks we need to control.
Board oversight
The Board has ultimate responsibility for the organisation’s internal controls and risk management framework. This includes approving the Risk and Assurance Strategy, setting the Risk Appetite Statement and ensuring strategic and operational decisions remain within agreed tolerances.
Committee assurance
The Audit and Assurance Committee provides detailed oversight of the Group’s risk management framework and system of internal control. It reviews the effectiveness of risk processes and independent assurance activities, working with internal audit, external audit and subject matter experts to ensure that principal risks are identified, evaluated and managed appropriately.
Supporting this framework, the Growth Committee provides oversight and assurance in relation to development, regeneration and growth activity, including the management of associated strategic and operational risks. The Customer Committee scrutinises customer outcomes, service performance and regulatory compliance, providing assurance on matters affecting customers and communities. The Remuneration and Appraisal Committee oversees risks relating to colleagues, leadership, organisational culture and reward arrangements.
Through their respective areas of responsibility, these committees provide assurance to the Board and contribute to the overall assessment of risk and control. The Audit and Assurance Committee retains responsibility for coordinating assurance across the Group and advising the Board on the overall effectiveness of the risk management and internal control framework.
How the framework works
Risk management and assurance work together. The framework identifies, assesses and mitigates significant risks, while independent checks confirm that controls are effective, proportionate and provide value for money.
Our approach continues to mature through Board and Audit and Assurance Committee oversight. It is structured around the recognised “three lines of defence” model and supported by an Assurance Map that links key risks to controls and assurance activity across the organisation.
Core stages
The risk management process is built around three core stages:
- Risk identification – recognising existing and emerging risks across strategic, operational, financial, and compliance areas
- Risk assessment – evaluating risks based on likelihood, impact, and alignment with risk appetite
- Risk mitigation and monitoring – implementing and tracking controls and mitigation actions
We maintain a forward-looking approach in response to financial pressure and wider economic and political uncertainty. Regular sensitivity and stress testing considers multi-variable scenarios, potential breaches of financial “golden rules” and agreed tolerance thresholds. Mitigation plans are reviewed and challenged by the Board to support resilience and informed decision-making.
Accessible alternative for Group Structure Chart
Top level
- Great Places Housing Group Ltd – Non-asset holding non-charitable RP (Registered Provider) Community Benefit Society with the following committees
- Remuneration and Appraisal Committee
- Audit and Assurance Committee
- Customer Committee
- Growth Committee (from 2025)
Level two
- Great Places Housing Association – 100% subsidiary asset-owning charitable, Community Benefit Society
- Plumlife Homes Limited- 100% subsidiary asset-owning charitable, Community Benefit Society
Level three (under Great Places Housing Association)
- Cube Homes Limited – Company limited by shares. Development of properties for outright sale and market rent
- Terra Nova Developments Limited – Company limited by shares. Design and build contracts – construction of rental property
Associate and minor shareholdings including two market sale JVs
Coterminous Board
At 1 April 2025, the group structure comprised four companies led by the Group board supported by three committees and managed by our Chief Executive and a team of Executive Directors.
99% of the group’s assets are owned by Great Places Housing Association.


